Editorial independence: our scores and rankings are produced using the fixed criteria above and are not influenced by advertisers. This is an independent ranking site and is not operated by, or affiliated with, any provider we list.
Affiliate disclosure: some links on this page may earn us a commission at no extra cost to you. This does not affect our rankings.
Live market data via CoinGecko, for informational purposes only. Not financial advice.
| Best for | Not for |
|---|---|
| Integrated borrowing, yield, exchange, and card ecosystem | Centralized custody and counterparty exposure |
Criteria Breakdown
| Criterion | Score | Notes |
|---|---|---|
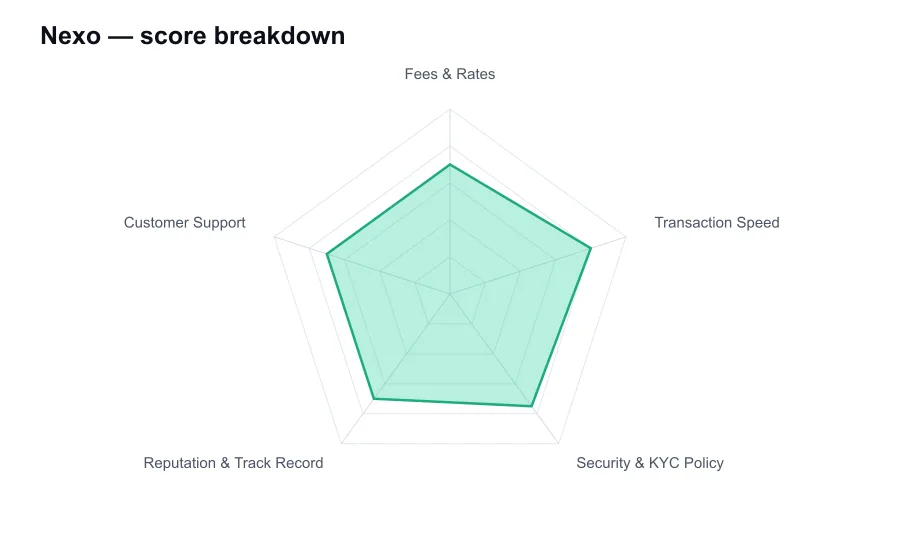
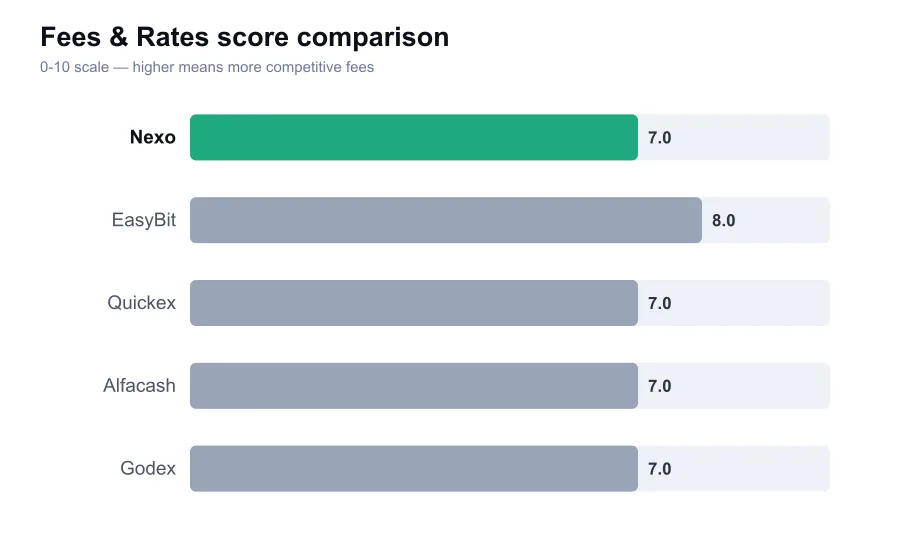
| Fees & Rates | 7.0 | Convenient swaps, but spreads and tier conditions affect real cost |
| Transaction Speed | 8.0 | Fast internal actions, external transfers depend on network checks |
| Security & KYC Policy | 7.5 | Established custodial controls and KYC, with counterparty risk |
| Reputation & Track Record | 7.0 | A notable survivor of crypto lending's difficult period |
| Customer Support | 7.0 | Live support options, though compliance cases can take time |
In-Depth Review
Nexo is a crypto financial platform built around lending, borrowing, savings-style yield products, card services, and spot-style exchange functionality. It is not trying to be a pure trading venue in the mold of Coinbase Advanced or Kraken Pro. Its central pitch has always been that crypto holders can keep exposure to their assets while borrowing against them, earning yield on supported balances, or spending through a card. That makes Nexo more comparable to a crypto wealth platform than a simple exchange.
The model is attractive because it addresses a real investor impulse: people often do not want to sell Bitcoin or Ether just to access liquidity. A collateralized loan can avoid a taxable disposal in some jurisdictions, though tax treatment depends entirely on local law and personal circumstances. It can also be dangerous. Borrowing against volatile assets magnifies the consequences of a market drop, and users should never treat a loan backed by crypto as free money.
Nexo's interface is polished and generally easier to navigate than many DeFi lending protocols. That convenience comes from centralization. The company manages the lending mechanics, custody, conversion process, and account controls behind the scenes. Users do not need to understand liquidation smart contracts or manage gas fees, but they are accepting counterparty risk and platform rules in exchange for that simplicity.
Its exchange service is useful for converting supported assets within the app, particularly for investors already using Nexo's other products. The exchange can source liquidity through an aggregated model, but it is not where serious day traders will find the most transparent order-book environment. The all-in quote matters more than a marketing claim about zero commissions. Spread, market conditions, pair availability, and trade size all influence the price a user actually receives.
Nexo advertises commission-free swaps in many cases, but commission-free should not be read as cost-free. A spread can still exist between the market midpoint and the execution price. For simple conversions of liquid coins, the convenience may justify that cost. For larger orders, active traders should compare the quote with a deep exchange before executing. This is one of those services that feels inexpensive until a user starts measuring fills carefully.
Borrowing costs are similarly more nuanced than the lowest advertised annual rate. Nexo's loan terms depend on collateral, loan-to-value ratios, loyalty tiers, and often whether users hold the platform's NEXO token. Low advertised rates may require conditions that do not suit every customer. A borrower should model the full scenario, including collateral volatility, interest, possible changes in token value, and the level at which liquidation risk becomes uncomfortable.
The yield side also needs a skeptical reading. Higher rates can be tied to fixed terms, loyalty levels, payout choices, asset type, or jurisdictional restrictions. Yield is not a magical property of crypto. It is compensation for lending, market, business, and counterparty risk. Nexo has a more developed product framework than many small yield platforms, but users should not deposit money simply because a displayed annual percentage looks better than a bank account.
Speed is one of Nexo's better qualities. Internal conversions, collateral adjustments, and loan-related actions are typically designed to happen quickly inside the platform. Card activity and internal transfers can also feel close to instant. External deposits and withdrawals are different. They depend on blockchain confirmation requirements, compliance screening, network congestion, and the asset being moved. Fast internal credit does not mean every external withdrawal will clear in minutes.
The company uses KYC and compliance controls, which should be expected from a centralized financial platform offering borrowing and card-related products. Account verification can include identity documentation and, for some activity, additional source-of-funds questions. That will be a dealbreaker for privacy-maximalist users, but it is part of the trade-off for a service seeking to operate with payment rails and regulated partners. Users should assume their account can be reviewed, limited, or closed under compliance policies.
Nexo's security posture is more substantial than that of many fly-by-night yield platforms. It has promoted custody arrangements, security practices, and insurance-related protections connected to third-party custodial infrastructure. Still, users should read these claims carefully. Insurance limits, policy exclusions, custodial structures, and the difference between a platform loss and a user account compromise all matter. No crypto platform should be treated as risk-free because it uses familiar security language.
Its reputation is complicated but stronger than its critics sometimes admit. Nexo has survived several major crypto credit failures that wiped out Celsius, BlockFi, Voyager, and others. That survival is meaningful. At the same time, the entire centralized lending sector was damaged by those collapses, and Nexo has faced regulatory pressure in some markets, including its departure from certain products or jurisdictions. A prudent customer should see both facts clearly.
The NEXO token introduces another layer of complexity. Loyalty benefits can improve rates or yields, but users should be cautious about buying a volatile platform token solely to qualify for a better offer. Doing so can concentrate risk in the same company whose services already hold your assets. Loyalty structures can be rational for users who understand the exposure, but they should not be mistaken for a free discount.
Customer support is reasonably accessible by crypto-platform standards, with help content, ticketing, and live-chat options often available. The experience can be good for routine questions, though complex compliance reviews and account restrictions are rarely resolved as quickly as customers would like. That is not unique to Nexo, but it is especially frustrating when a platform also controls collateral. Users should keep records, avoid last-minute loan management, and leave a buffer before any important payment deadline.
Nexo is best for users who understand centralized lending and want a relatively mature all-in-one crypto finance product. It is less attractive for traders demanding transparent market structure, privacy-oriented users, or anyone who cannot tolerate the possibility of account reviews and changing jurisdictional availability. My own stance is cautious but not dismissive. Nexo is one of the more credible survivors in a damaged category, yet its convenience does not erase the risks that made crypto lending so hazardous in the first place.
Pros & Cons
| Pros | Cons |
|---|
Does Nexo charge trading fees?
Nexo often markets swaps as commission-free, but the execution quote can include a spread. Compare the amount received with an external exchange, especially for larger conversions or less liquid assets.
Is borrowing from Nexo risky?
Yes. A crypto-backed loan can face liquidation pressure if collateral falls in value. Rates, loan-to-value limits, and collateral requirements should be understood before borrowing.
Does Nexo require KYC?
Yes. Nexo is a centralized financial platform and users should expect identity verification and potentially additional compliance checks for certain transactions or account activity.
Can users withdraw crypto from Nexo?
Supported assets can generally be withdrawn externally, subject to network conditions, account verification, withdrawal rules, and any compliance review. Timing is not the same as an internal platform transfer.